Information
About
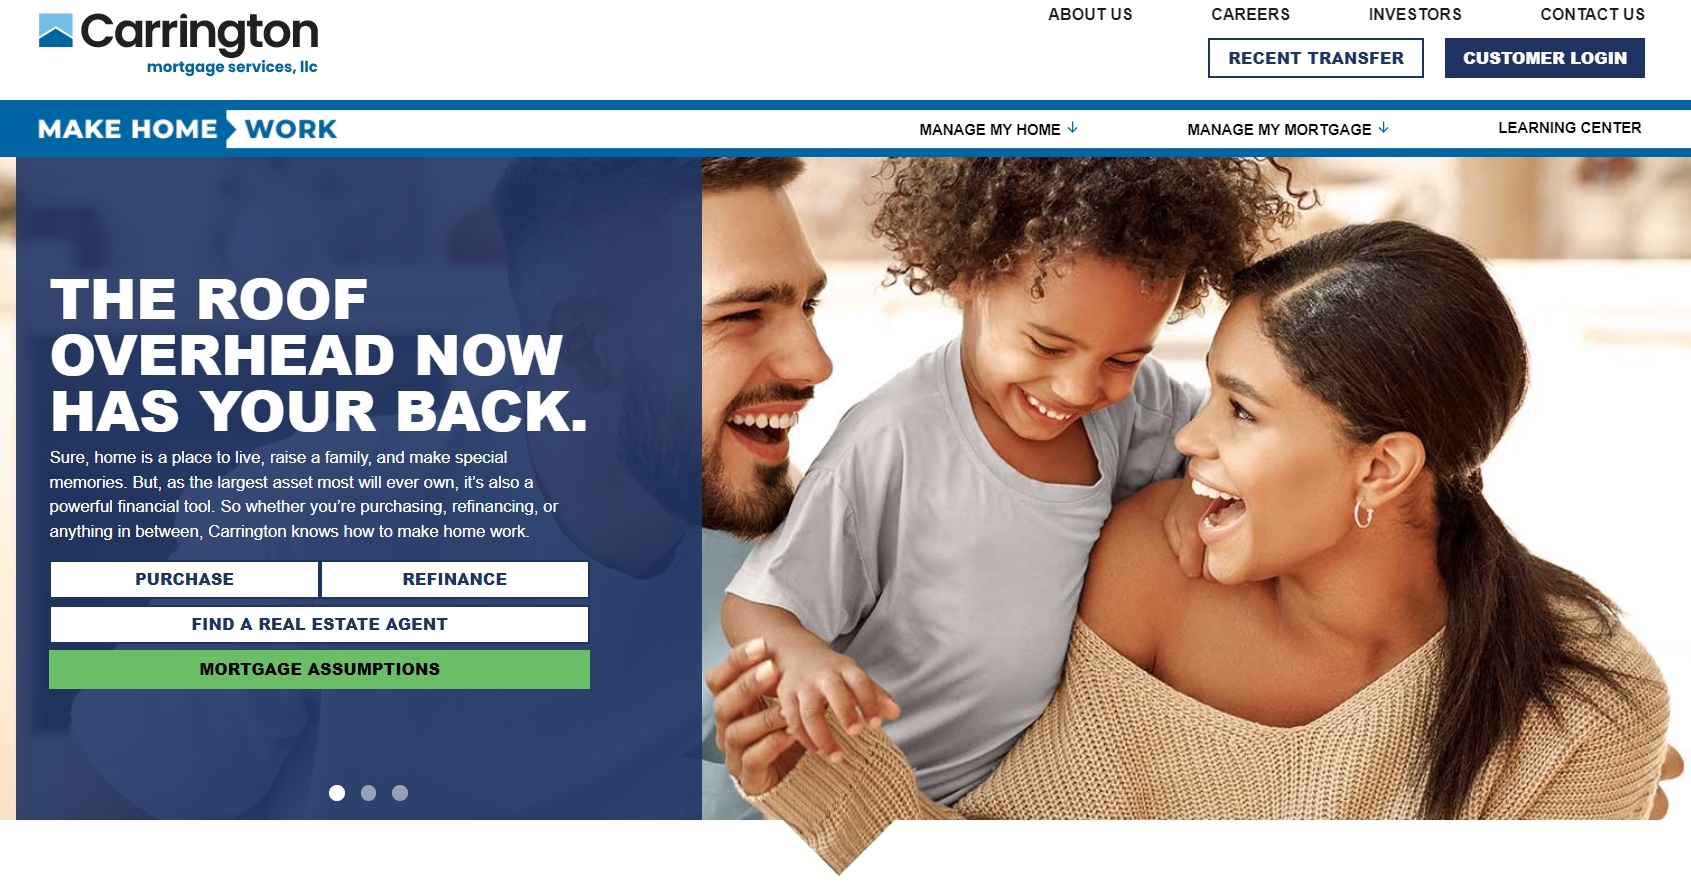
Carrington Mortgage is a mortgage lender and broker that offers a range of home loan products to borrowers across the United States. The company was founded in 2003 and is headquartered in Anaheim, California.
Carrington Mortgage offers a variety of loan products, including conventional loans, FHA loans, VA loans, USDA loans, jumbo loans, and refinancing options. The company is known for offering loans to borrowers with less-than-perfect credit or who have had difficulty qualifying for loans from other lenders.
In addition to its lending services, Carrington Mortgage also operates as a mortgage broker, allowing borrowers to compare loan products and interest rates from multiple lenders. The company's website offers a range of online tools and resources, including a mortgage calculator, a glossary of mortgage terms, and a step-by-step guide to the home buying process.
Carrington Mortgage is committed to providing a high level of customer service and support to its borrowers, with a team of loan officers and customer service representatives available to assist borrowers throughout the loan process. The company has received high ratings from third-party review sites and is accredited by the Better Business Bureau.
Overall, Carrington Mortgage is a reputable and reliable mortgage lender and broker that offers a range of loan products and services to borrowers across the United States.
Key Features
Carrington Mortgage Services is a financial institution that offers a range of home loan products and services. Some of the key features of Carrington Mortgage include:
- Flexible Loan Programs. Carrington Mortgage offers a variety of loan programs, including conventional, FHA, VA, and USDA loans. They also offer specialized programs, such as their Flexible Advantage program for borrowers with lower credit scores.
- Streamlined Application Process. Carrington Mortgage offers an online application process that is designed to be quick and easy. Applicants can submit their application and receive a decision in as little as 24 hours.
- Low Down Payment Options. Carrington Mortgage offers low down payment options for many of their loan programs. For example, they offer FHA loans with a minimum down payment of 3.5%.
- Credit Score Requirements. Carrington Mortgage has flexible credit score requirements for some of their loan programs. For example, their Flexible Advantage program may accept credit scores as low as 500.
- Personalized Customer Service. Carrington Mortgage is committed to providing personalized customer service to their clients. They have a team of loan officers who can help borrowers find the right loan program for their needs and answer any questions they may have.
- Servicing Capabilities. Carrington Mortgage services many of the loans they originate, meaning they will continue to work with borrowers throughout the life of their loan. This can be especially beneficial for borrowers who may need assistance or have questions after closing on their loan.
Overall, Carrington Mortgage Services offers a range of loan programs and personalized customer service to help borrowers find the right loan for their needs.
Pros and Сons
Pros
- Flexible loan programs. Carrington Mortgage offers a variety of loan programs, including specialized options for borrowers with lower credit scores.
- Streamlined application process. The online application process is quick and easy, and applicants can receive a decision in as little as 24 hours.
- Low down payment options. Carrington Mortgage offers low down payment options for many of their loan programs, making homeownership more accessible to a wider range of borrowers.
- Personalized customer service. Carrington Mortgage is committed to providing personalized customer service to their clients, with a team of loan officers who can help borrowers find the right loan program for their needs.
- Servicing capabilities. Carrington Mortgage services many of the loans they originate, providing borrowers with continued support and assistance throughout the life of their loan.
Cons
- Limited physical branch locations. Carrington Mortgage has a limited number of physical branch locations, which may be inconvenient for some borrowers who prefer to work with a lender in person.
- Higher interest rates and fees. Some borrowers have reported that Carrington Mortgage's interest rates and fees are higher than those of other lenders.
- Limited information on website. Some borrowers have noted that the Carrington Mortgage website lacks detailed information about their loan programs and services, which can be frustrating for those trying to compare options.
- Potential for loan servicing issues. While Carrington Mortgage services many of the loans they originate, some borrowers have reported issues with loan servicing, including late fees and inaccurate information on their account.
- There is no option to apply for home equity lines of credit (HELOCs).
Products
Carrington Mortgage offers a range of loan products and services to help borrowers find the right mortgage for their needs. Some of their primary products include:
- Conventional loans. Conventional loan standards are the strictest. You need a good credit score and low debt-to-income ratio to get the best rates and terms. Carrington offers 30-year and 15-year fixed-rate loans. A fixed-rate loan has a constant interest rate, meaning your monthly principal and interest payments won't change.
- FHA loans. Carrington Mortgage offers Federal Housing Administration (FHA) loans, which are designed to help first-time homebuyers and low-to-moderate-income borrowers access affordable financing with low down payments and flexible credit requirements.
- VA loans. Carrington Mortgage offers VA loans, which are guaranteed by the Department of Veterans Affairs (VA) and are available to eligible veterans, service members, and surviving spouses. These loans offer low or no down payment options, competitive interest rates, and flexible credit requirements.
- USDA loans. Carrington Mortgage offers United States Department of Agriculture (USDA) loans, which are designed to help rural and suburban homebuyers access affordable financing with no down payment and low interest rates.
- Jumbo loans. Jumbo loans surpass Fannie Mae and Freddie Mac's loan limits. Location-based restrictions range from $548,250 to $822,375. Jumbo loans can finance up to 80%, requiring a 20% down payment. Carrington provides $2.5 million jumbo loans.
- Refinance loans. Carrington Mortgage also offers refinance loans for borrowers who want to lower their interest rate, shorten their loan term, or access their home's equity for other expenses.
Overall, Carrington Mortgage offers a variety of loan products to help borrowers find the right mortgage for their unique needs and circumstances.
Reliability
Carrington Mortgage is a licensed mortgage lender and servicer, and the company has been in business for over a decade. The company is a member of the National Mortgage Licensing System (NMLS) and is licensed to operate in all 50 states.
In terms of customer satisfaction and reliability, Carrington Mortgage has a mixed reputation. The company has received both positive and negative reviews from customers, with some borrowers praising the company's personalized customer service and others criticizing the company's loan processing times and servicing practices.
Carrington Mortgage has a rating of "A+" with the Better Business Bureau (BBB), and the company has been accredited with the BBB since 2012. However, the company has received a significant number of customer complaints through the BBB, many of which relate to issues with loan servicing and customer service.
Overall, while Carrington Mortgage is a licensed and reputable lender, borrowers should carefully research the company and read reviews from other customers before deciding whether to work with them. Borrowers should also compare loan options from multiple lenders to ensure they are getting the best rates and terms for their individual needs.
Funding a Loan
Carrington Mortgage funds loans through a variety of sources, including its own funds and funds from institutional investors, such as hedge funds, pension funds, and other financial institutions. The company uses a network of mortgage brokers and loan officers to originate loans and then processes, underwrites, and funds the loans in-house.
When a borrower applies for a loan with Carrington Mortgage, the company's loan officers and underwriters will review the application and the borrower's financial information to determine whether the borrower meets the company's underwriting guidelines. If the borrower is approved for a loan, Carrington Mortgage will work with the borrower to finalize the loan terms and conditions and will fund the loan once all the necessary documentation has been received.
Carrington Mortgage also offers loan servicing, which means that the company collects and manages the borrower's loan payments over the life of the loan. The company may sell the servicing rights to a third party, but the borrower's loan terms and conditions will not change as a result of the sale.
Overall, Carrington Mortgage uses a combination of its own funds and funds from institutional investors to fund loans, and the company offers loan servicing to help borrowers manage their loan payments over time.
Additional Services
In addition to mortgage loans, Carrington Mortgage also offers a range of additional services to help borrowers throughout the homebuying process. These services include:
- Real estate services. Carrington Mortgage offers real estate services through its sister company, Carrington Real Estate Services. This includes a nationwide network of real estate agents who can help borrowers buy or sell a home.
- Home refinancing. Carrington Mortgage offers home refinancing options to help borrowers lower their monthly mortgage payments, reduce their interest rates, or access their home equity.
- Home buying grants. The company offers home buying grants through its Carrington Charitable Foundation to help eligible borrowers cover down payment and closing costs.
- Home warranty services. Carrington Mortgage partners with Home Warranty of America to offer home warranty services to borrowers, which can help protect them from unexpected repair costs.
- Home protection services. The company offers home protection services through its Home Protection Plan, which covers major systems and appliances in the home.
- Reverse mortgages. Carrington Mortgage offers reverse mortgage options for eligible borrowers who are 62 years or older and have significant home equity.
Overall, Carrington Mortgage offers a range of additional services to help borrowers through every step of the homebuying process, from real estate services to home warranty and protection services. Borrowers should carefully review the terms and conditions of these additional services to determine whether they are a good fit for their individual needs.
Terms and conditions
The specific terms and conditions of a Carrington Mortgage loan will depend on the type of loan and the borrower's individual circumstances. However, some common terms and conditions that borrowers can expect to encounter when working with Carrington Mortgage include:
- Loan amounts. The amount a borrower can borrow will depend on the type of loan they are seeking, their creditworthiness, and other factors. Carrington Mortgage offers a range of loan amounts to meet borrowers' needs.
- Interest rates. The interest rate on a Carrington Mortgage loan will depend on a variety of factors, including the type of loan, the borrower's credit score, and current market conditions.
- Loan terms. The length of a Carrington Mortgage loan can vary depending on the type of loan and other factors. Conventional loans typically have terms of 15 or 30 years, while other loan types may have different terms.
- Fees. Carrington Mortgage may charge fees for origination, processing, underwriting, and other loan-related services. These fees will vary depending on the type of loan and the borrower's individual circumstances.
- Prepayment penalties. Some Carrington Mortgage loans may include prepayment penalties if the borrower pays off the loan early. Borrowers should carefully review their loan agreement to understand any prepayment penalty terms.
- Default and foreclosure. If a borrower fails to make timely loan payments, their loan may go into default and may be subject to foreclosure. Borrowers should carefully review their loan agreement to understand the terms and conditions related to default and foreclosure.
- Eligibility requirements. Carrington Mortgage may have specific eligibility requirements for each loan product, including credit score, income, and other factors. Borrowers should carefully review the eligibility requirements for each loan product they are considering to determine whether they are a good fit.
Overall, borrowers should carefully review the terms and conditions of their Carrington Mortgage loan agreement and ask any questions they may have to ensure they understand the terms of their loan.
Carrington Mortgage vs United Wholesale Mortgage
Carrington Mortgage vs Mutual of Omaha Mortgage
Carrington Mortgage vs Shellpoint
Carrington Mortgage vs RoundPoint Mortgage