How to apply for a loan?
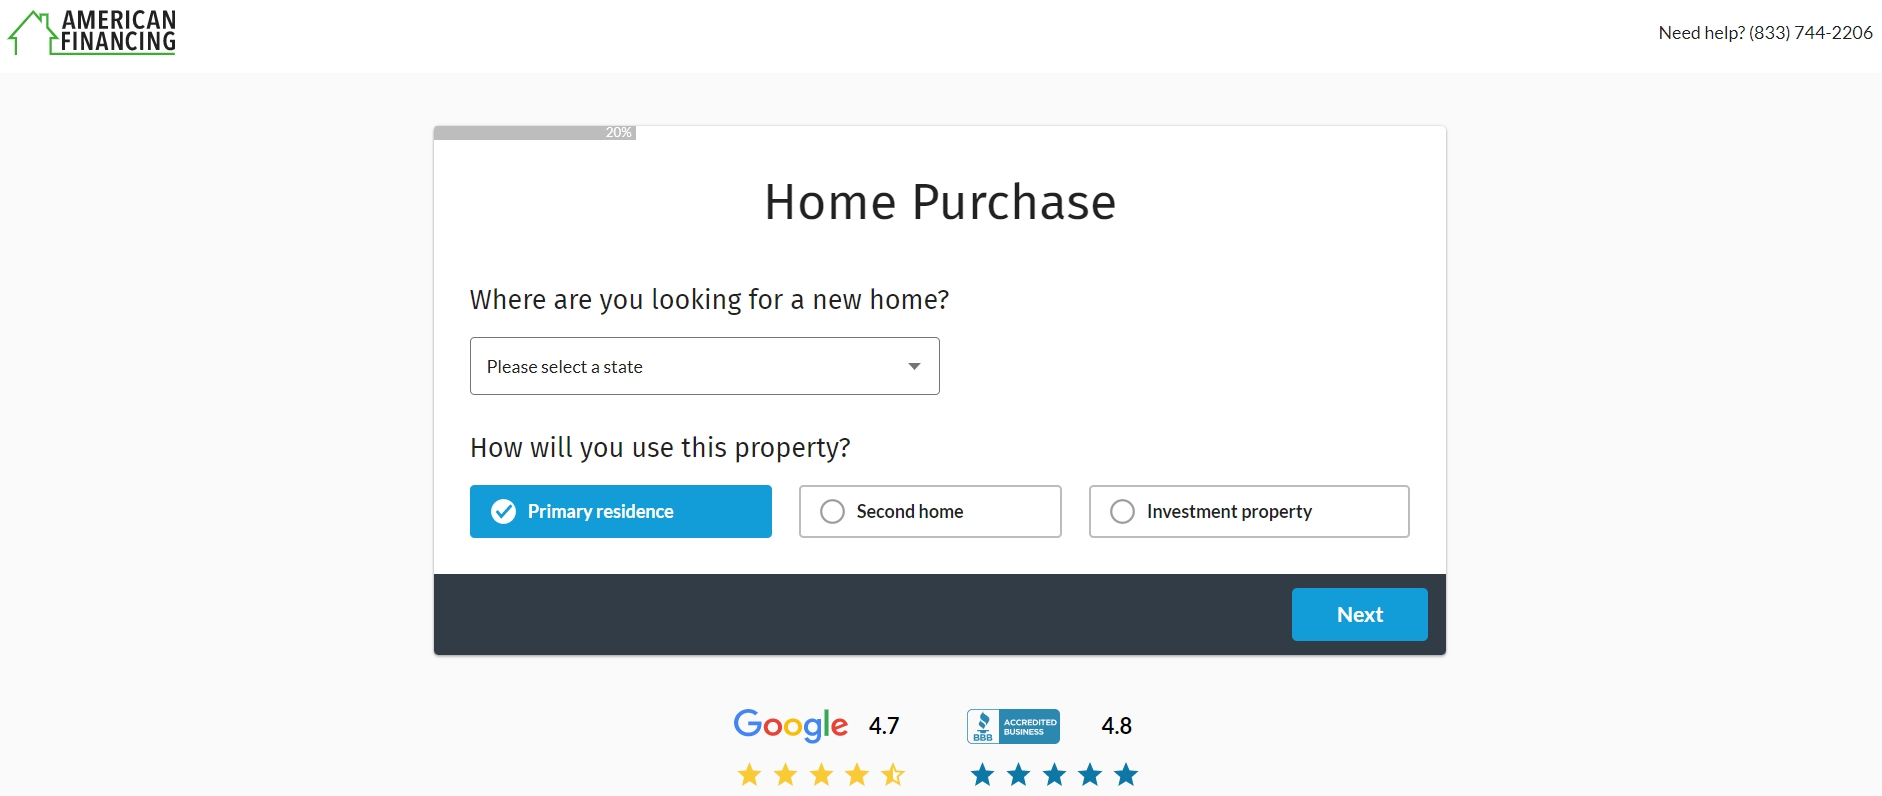
To apply for financing, you need to follow a few simple steps:
- Click on the "Get Started" button;
- Select the state where the desired property is located, the type of property, and click "Next";
- Choose the amount of the future mortgage;
- Enter the amount or percentage of the down payment;
- Fill in your name, email, and phone number;
- Click "Continue Online";
- Choose the type of house;
- Confirm the entered early data and select the source of the first payment;
- Answer questions about the realtor and the ownership of other houses earlier;
- Enter your residential address;
- Select the type of employment and enter data about the company name, start date, and annual income;
- Enter information about financial assets;
- Enter demographic information as desired;
- Answer questions about bankruptcy;
- Enter your date of birth and SSN.
Requirements
To obtain approval of the application, the borrower must:
- Have 580 FICO credit score for FHA loan, 620 for VA loan and for Cash-Out refinance, and 700 for 15 year-mortgage;
- Be 18+ years old;
- Be a US citizen or permanent resident;
- Have a provable source of income.
To obtain an FHA loan, the borrower must additionally:
- Have two years of stable employment;
- Have a debt-to-income ratio of no more than 43%;
- Have 30% of income available for a mortgage payment;
- Have less than 30 days of late payment of debts for the last two years.
To receive a VA loan, the borrower must serve at least:
- 181 days in peacetime;
- 90 consecutive days during the war;
- Six years in the National Guard or the Reserves.
Application details
To complete the application, the borrower must provide these additional documents:
- W2s for the last two years;
- Tax Returns for the last two years;
- Photo of the government-issued ID;
- Pay stubs covering the last 30 days;
- Wet Signed Borrower's Certification;
- Wet Signed SSA-89.
In case of refinancing, these documents are also required:
- Homeowners Insurance Declaration page;
- Mortgage statement.
The most common reasons for refusal are bad credit, no credit, high debt-to-income ratio, and insufficient down payment.